By Stacker
- Only 42% of small business loan applicants received the full funding they applied for in 2026, with personal credit score cited as the most common reason for denial
- Knowing which loan matches your startup stage before you apply could be the difference between approval and months wasted on a dead end application
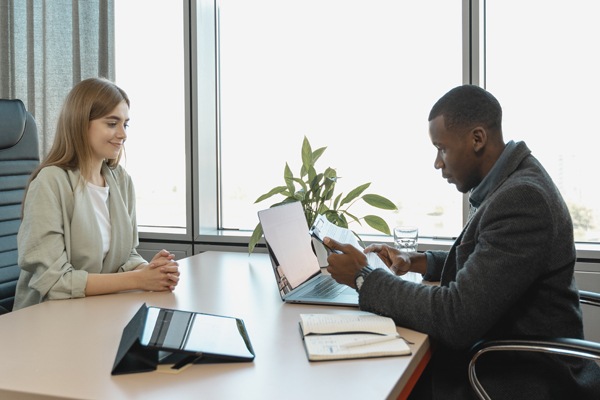
Getting a business loan in 2026 is not about finding the right bank. It is about knowing which product matches where your business actually is right now. For founders, CEOs, and early finance leads trying to preserve runway, applying for the wrong loan at the wrong stage is the most common and most avoidable mistake.
Why This Matters: Lenders review six core factors on every application: personal credit score, time in business, revenue and repayment capacity, collateral and personal guarantee, equity injection, and business purpose. For startups, personal credit carries the most weight because there is no operating history to fall back on. Many SBA 7(a) lenders look for scores of 600 to 670 or higher.
If your business is pre-revenue, the most realistic entry point is an SBA microloan through a Community Development Financial Institution or CDFI. These nonprofit lenders set their own credit requirements and underwrite on founder profile and projections rather than years of revenue — making them specifically designed for the stage most first-time founders are actually at. Black-owned firms are already twice as likely to be denied business loans as white-owned firms. Applying for the wrong product at the wrong stage only widens that gap.
What’s Next: 60 to 90 days of preparation before applying can dramatically improve your odds. Pull your personal credit report and resolve errors first. Separate business and personal finances immediately. Build cash flow projections backed by real contracts or pipeline data rather than spreadsheet assumptions. Then match the loan to your actual stage. Pre-revenue founders should start with CDFIs. Early-revenue founders can explore SBA loans and online term loans. Venture-backed founders should look at venture debt. The fastest path to funding is not the biggest loan. It is the right one for where you are right now.
CBx Vibe: “Started From the Bottom” Drake