By Stacker
- The new Trump account allows families to save up to $5,000 annually for children tax-deferred, with a one-time $1,000 government contribution for children born between 2025 and 2028
- Despite the college savings framing, Trump accounts are better suited as long-term retirement tools, and knowing the difference could save families thousands
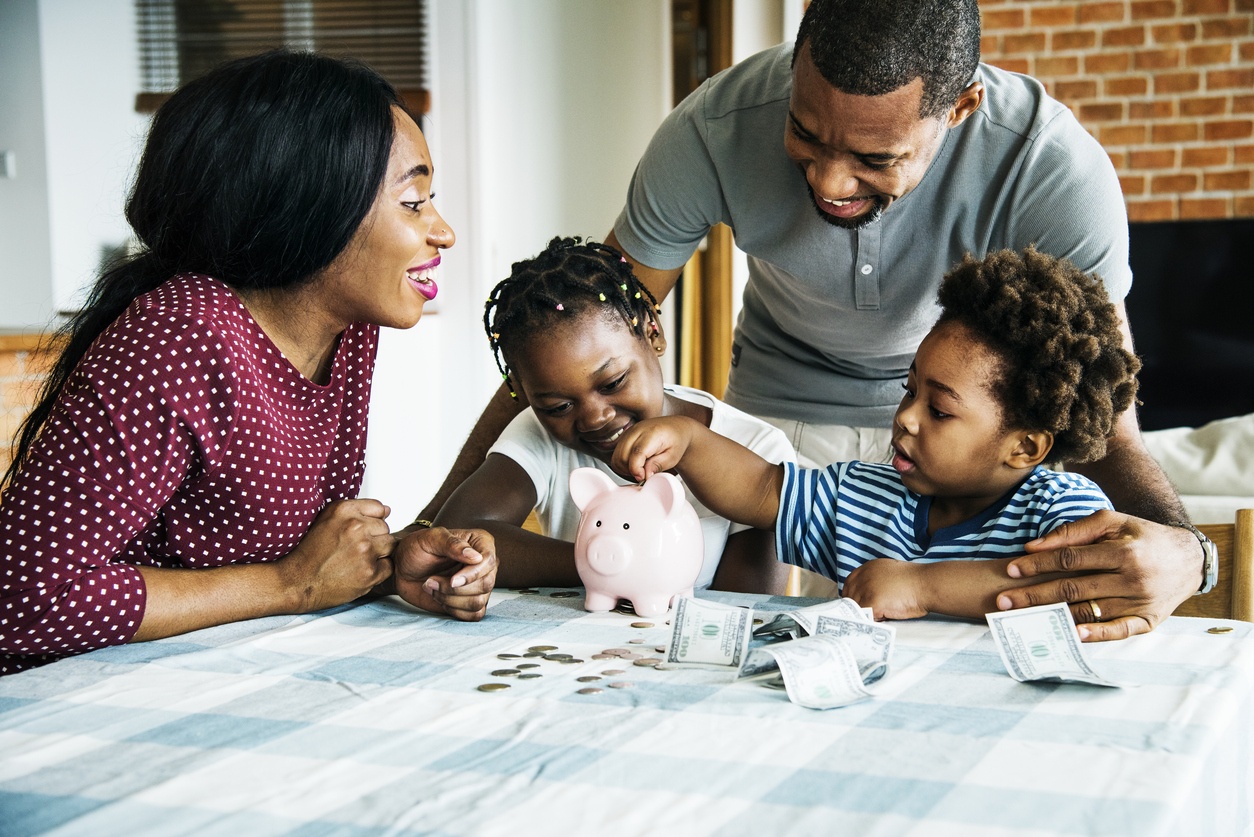
Last year’s tax legislation introduced a brand new savings vehicle for families: the Trump account. Designed to help parents set aside money for their children, the account comes with tax-deferred growth, government seed money, and strict rules that make it very different from the college savings tools most families already know. Understanding exactly what it is, and what it is not, could be one of the most important financial decisions a family makes this decade.
Why This Matters: For Black families working to close the generational wealth gap, every tax-advantaged savings tool matters. The Trump account allows contributions of up to $5,000 annually from families and employers, with a one-time $1,000 government contribution for children born between 2025 and 2028. During the growth phase, which runs until the child turns 17, the account can only invest in low-cost index funds tracking broad U.S. equity indexes. No distributions are allowed during this period.
At age 18, the account converts and operates under traditional IRA rules, meaning withdrawals are taxed as ordinary income and early distributions before age 59 and a half trigger a 10% penalty. For education funding, a 529 plan remains far superior. A family contributing $5,000 annually for 18 years ends up with roughly $213,000 in both a 529 and a Trump account, but the 529 delivers the full balance tax-free for education, while the Trump account leaves only about $174,500 after taxes. That is a $38,500 difference on the same contribution.
What’s Next: Trump accounts shine brightest as long-term retirement vehicles, not education funds. For families with children who have decades ahead of them, the tax-deferred compounding can build meaningful wealth by retirement age. But the 10% early withdrawal penalty means the account only outperforms a standard custodial UTMA account after roughly 59 years of growth. The takeaway is simple: use a 529 for college, and consider a Trump account only as a supplemental retirement starter for your child. Start early, contribute consistently, and do not touch it.
CBx Vibe: “Glory” Jay-Z featuring Blue Ivy Carter